Despite Good Earnings, Bank Balance Sheets Are Weakening Under The Hood
 By
Avi Gilburt
The recent FDIC Quarterly Banking Profile confirmed that the US banking sector balance sheet continues to deteriorate in some important areas despite a quite benign environment. Clearly, the system is moving in the wrong direction even before the credit cycle has entered a negative phase.
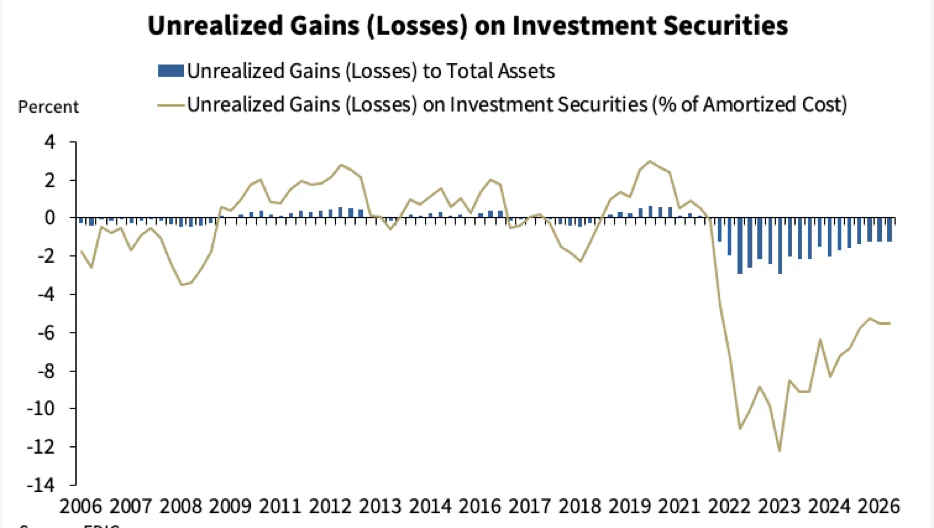
First, unrealized securities losses increased in the second quarter to $327BN. As a reminder, Bank of America's consolidated unrealized securities losses are roughly equivalent to one-quarter of the FDIC industry total, which is quite a striking number for one bank. Unrealized securities losses are becoming an increasingly concerning factor for the system, especially given renewed pressure from higher long-term UST yields. Bank management teams continue saying that they are going to hold these securities to maturity, but much of this exposure is long-dated. When a crisis comes, these underwater bonds cannot be freely sold or repositioned without realizing significant losses, which, of course, creates a liquidity problem precisely when liquidity is needed most.
Second, this becomes considerably more uncomfortable when the capital cushion is simultaneously shrinking relative to the balance sheet. The Tier 1 risk-based capital ratio fell by 17 bps QoQ in the second quarter to 13.75%, while the leverage ratio also fell by 17 bps QoQ to 8.98%.
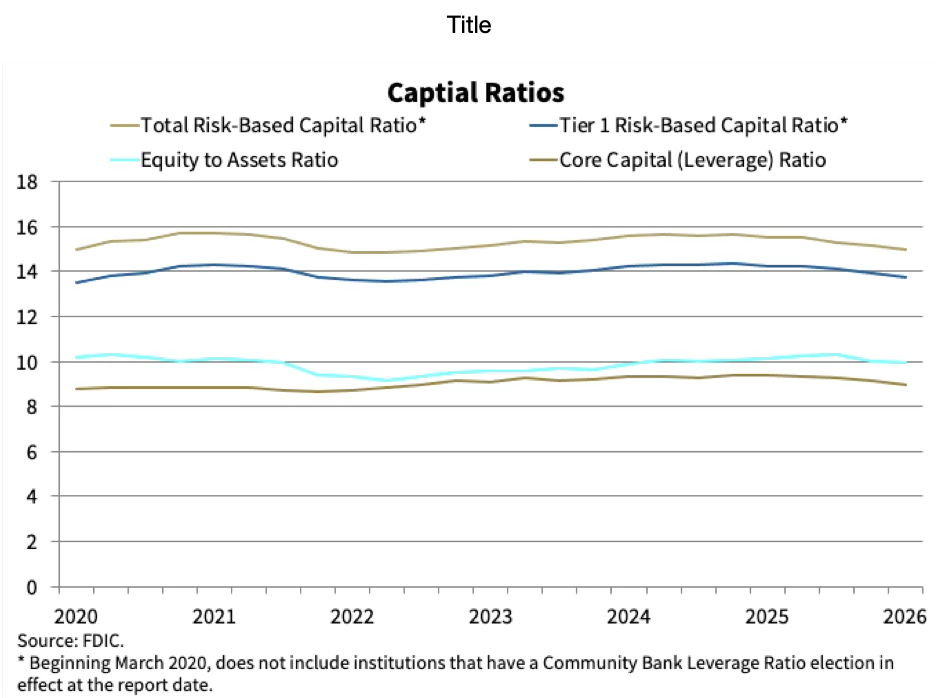
Importantly, this is happening in a good phase of the credit cycle, which is quite concerning. The FDIC said this was because "asset growth outpaced capital accretion." And this was not a weak earnings quarter as the industry generated $90bn of earnings and a 1.4% ROA.
Even more troubling, the largest increase in loans came from shadow lending. If you follow our banking work, you know that lending to shadow banks has been one of the biggest growth engines in the US banking system of late. If capital ratios are already falling in this part of the credit cycle, that is a major concern given the system is overdue for its down cycle.
This creates a potentially dangerous asymmetry. Higher long-term rates keep securities losses trapped on balance sheets and constrain liquidity, while the capital cushion available to absorb future losses is becoming smaller and smaller. Moreover, this is happening against a backdrop of major asset quality issues in CRE, credit cards, auto loans, and shadow banking. That is precisely the combination that can turn an otherwise manageable credit or liquidity event into a capital/solvency event.
Bottom line
Believe it or not, there are more major issues on the larger bank balance sheets as compared to smaller banks, which we have covered in past articles. Moreover, consider that there was one major issue which caused the GFC back in 2008, whereas today, we currently have many more large issues on bank balance sheets. These risk factors include major issues in commercial real estate, rising risks in consumer debt (approaching 2007 levels), underwater long-term securities, over-the-counter derivatives, high-risk shadow banking (the lending for which has exploded), and elevated default risk in commercial and industrial (C&I) lending. So, in our opinion, the current banking environment presents even greater risks than what we have seen during the 2008 GFC.
Almost all the banks that we have recommended to our clients are community banks, which do not have any of the issues we have been outlining over the last several years. Of course, we're not saying that all community banks are good. There are a lot of small community banks that are much weaker than larger banks. That’s why it's absolutely imperative to engage in a thorough due diligence to find a safer bank for your hard-earned money. And what we have found is that there are still some very solid and safe community banks with conservative business models.
So, I want to take this opportunity to remind you that we have reviewed many larger banks in our public articles. But I must warn you: The substance of that analysis is not looking too good for the future of the larger banks in the United States, and you can read about them in the prior articles we have written.
Moreover, if you believe that the banking issues have been addressed, I think that New York Community Bank is reminding us that we have likely only seen the tip of the iceberg. We were also able to identify the exact reasons in a public article which caused SVB to fail. And I can assure you that they have not been resolved. It's now only a matter of time before the rest of the market begins to take notice. By then, it will likely be too late for many bank deposit holders.
At the end of the day, we're speaking of protecting your hard-earned money. Therefore, it behooves you to engage in due diligence regarding the banks which currently house your money.
You have a responsibility to yourself and your family to make sure your money resides in only the safest of institutions. And if you're relying on the FDIC, I suggest you read our prior articles, which outline why such reliance will not be as prudent as you may believe in the coming years, with one of the main reasons being the banking industry’s desired move towards bail-ins. (And, if you do not know what a bail-in is, I suggest you read our prior articles.)
It's time for you to do a deep dive on the banks that house your hard-earned money in order to determine whether your bank is truly solid or not. You can feel free to review our due diligence methodology here.